Originally Published: · Last Updated:
How to read a 10-K depends on why you opened it. Use a broad first pass when you are learning a company. For an annual review, compare the business, risks, the company’s explanation, financial statements, notes, audit report, and controls. Do not treat any three sections as a complete substitute for the filing. Go deeper when a change in one section is not explained by the others.
A 10-K can feel like a test of endurance. Start with the decision you are trying to make and the disclosures that could change it.
Suppose the earnings call sounded clean and you may add to the position. Finishing the filing is not the outcome that matters. You need to know whether the business, cash flow, risks, accounting choices, and controls still support the reason you own the stock.
The SEC describes the 10-K as a detailed account of a company’s business, risks, results, and financial condition. It includes management’s view of what drove those results. The SEC does not write the filing or vouch for its accuracy. The company prepares it, and its CEO and CFO certify it. The auditor reports on the financial statements and, for many issuers, internal control over financial reporting.
That makes a 10-K more than a longer earnings release. It is where the polished story meets required disclosure, accounting detail, audited financial statements, and the auditor’s report.
Choose the Right 10-K Reading Mode
Before deciding what to read first, decide whether you are learning the company, reviewing an existing holding, or checking a warning sign. Those jobs call for different levels of detail.
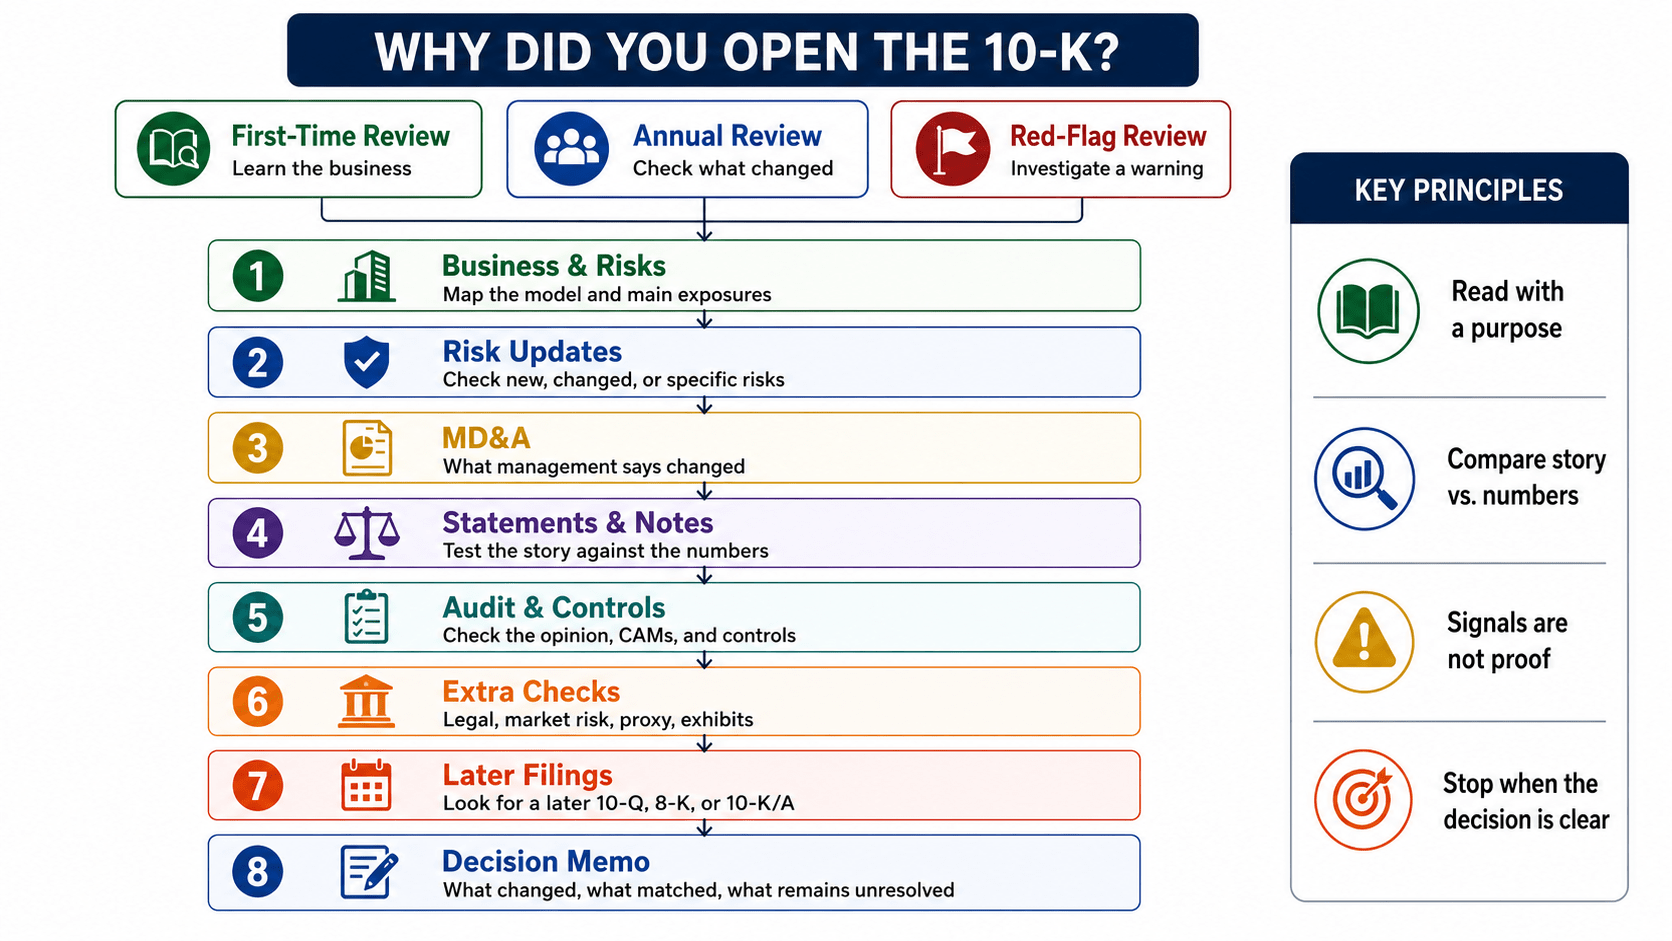
Most bad advice about how to read a 10-K assumes every reader has the same job. If you want to read a 10-K efficiently, first separate a first-time review, an annual review, and a red-flag check. A first-time buyer needs a map of the company. A long-time shareholder needs to find what changed. Someone checking a possible accounting or solvency problem should follow the issue wherever it appears, including the notes, auditor’s report, controls, legal proceedings, and exhibits.
| Reading mode | Start here | What should change your decision |
|---|---|---|
| First-time review | Item 1 Business, Item 1A Risk Factors when present, segment and geographic notes | You cannot explain how the company makes money, where it is exposed, or which assumptions the thesis requires |
| Annual holding review | Prior-year filing, current Item 1A when present, Item 7 MD&A, Item 8 statements and notes | A new risk, changed accounting estimate, weakening cash conversion, or unexplained shift in margins or capital needs |
| Red-flag check | The disclosure that raised the concern, then related notes, audit report, Item 9, Item 9A, and exhibits | A qualified or adverse opinion, a disclaimer of opinion, a material weakness, auditor disagreement, liquidity pressure, covenant issue, or inconsistent disclosure |
A study by Dyer, Lang, and Stice-Lawrence is sometimes cited to support a three-section shortcut. Their evidence does not support that leap. The researchers found that median 10-K text in their sample rose from about 23,000 words in 1996 to nearly 50,000 in 2013. Three disclosure topics explained most of that increase: fair value and impairment, internal controls, and risk factors. But those topics appeared across major sections of the filing. The study did not show that three numbered sections contain all the evidence an investor needs.
Evidence: Dyer, Lang, and Stice-Lawrence studied 75,991 firm-years from 1996 through 2013 and explicitly noted that the growing topics were not confined to a single section. Read the paper.
Longer filings still create a real processing problem. A better response is to choose a reading mode, keep the prior-year filing open, and follow material changes across sections.
Start With the Business and Risk Map
A practical answer to how to read a 10-K starts with Item 1 and Item 1A when the company is new to you. This first pass maps the business model and the conditions that could break it.
Read Item 1 before judging the numbers
The SEC calls the Business section a good place to start. Read it until you can answer a few plain questions about the business. Identify what the company sells, who pays it, which segments matter, and which assets or suppliers are key. Then ask whether growth comes from volume, price, a deal, or a change in mix.
The business model is the map that makes later numbers easier to read. The statements become easier to read once you know which business drivers should show up in revenue, margins, working capital, capital spending, and segment results.
Write a one-sentence business model before moving on. A useful version names the customer, the product or service, the main profit driver, and the biggest dependency. When you cannot do that, you are not ready to value the company.
Use Item 1A to challenge the investment thesis
Do not reduce Risk Factors to a word count or score. When Item 1A is required and present, compare it with the prior year and look for changes in detail, emphasis, and placement. A newly added risk or more concrete language can matter more than a paragraph that appears every year. Reordering is a reason to check further, not proof that the company has formally ranked one risk above another. Smaller reporting companies are not required to provide Item 1A.
Campbell and coauthors found that firms facing greater risk disclosed more risk factors, and that the type of disclosure varied with the kind of risk the firm faced. The study also found that market participants used those disclosures when judging firm risk and stock price. That does not make every sentence useful. It does give you a reason to look for changes tied to that company instead of dismissing the whole section as boilerplate.
Evidence: Campbell, Chen, Dhaliwal, Lu, and Steele examined mandatory risk-factor disclosures and found that their content reflected the type and level of firm risk. Review the paper and abstract.
Also check other filing sections when they can affect the thesis. Item 1B can contain open SEC staff comments when the form requires that disclosure. Item 1C covers cyber risk management, strategy, and governance under Regulation S-K Item 106. If cyber risk could materially affect the business, customers, data, or financing, read Item 1C with the related risk factors. Do not treat it as a separate compliance topic.
Connect the risk language to the original thesis. If your thesis rests on a durable economic moat, pay attention when the filing describes weaker pricing power, rising customer concentration, or greater supply dependence. If those risks are rising, look for a credible offset. The filing may not tell you what the stock is worth, but it can show that the story you were valuing has changed.
Connect MD&A to the Financial Statements
Item 7 explains the company’s view of performance and liquidity, while Item 8 supplies the audited statements and notes. Read them together because a reason without the numbers is incomplete, and a number without its accounting context can mislead.
Read MD&A for causes, not adjectives
MD&A should explain what changed in the business, liquidity, capital resources, key estimates, and known trends or risks. Ignore words such as strong, resilient, disciplined, or short-lived until the filing shows what drove the change. Write down the reason the company gives.
Next, see whether that reason appears elsewhere in the filing. If the company credits demand for revenue growth, check unit volume, price, backlog, customer concentration, and accounts receivable. If the company calls a margin decline short-lived, inspect inventory, restructuring costs, purchase commitments, and the assumptions behind impairment or reserve estimates.
At this point, page order matters less than the cross-check. Ask whether the company’s reason fits the filed numbers and notes.
A quick reconciliation example: Suppose the company attributes revenue growth to stronger demand, but accounts receivable rise much faster than sales and operating cash flow weakens. That mismatch is not proof of misconduct. It is a reason to open the revenue and allowance notes, check whether payment terms or customer concentration changed, and ask whether the cash pattern supports the company’s story.
Read Item 8 as a connected system
Item 8 includes the financial statements, notes, and auditor’s report. Do not stop at net income; trace the same business story through the income statement, balance sheet, cash flow statement, equity statement, and key footnotes.
- Income statement: Did growth come with stable or better margins, or did expenses and one-time adjustments do the work?
- Balance sheet: Did receivables, inventory, debt, deferred revenue, goodwill, or other assets move faster than the business explanation would suggest?
- Cash flow statement: Did reported earnings convert into operating cash, and what working-capital movements explain the difference?
- Stockholders’ equity: Did buybacks, share issuance, share-based pay, past losses, or other equity changes alter the ownership or capital story?
- Notes: Which estimates, segment rules, commitments, legal claims, stock pay, pensions, taxes, or deals materially affect the headline numbers?
This cross-check ties the main statements together. Use the income statement guide when margins and expense labels are the issue. Use the cash flow statement guide when earnings and cash move in different directions.
Do not use a fixed cash-conversion threshold across every industry. Banks, insurers, asset-heavy makers, subscription businesses, and fast-growing retailers can have very different working-capital patterns. Compare the company with its own history and similar firms before calling a gap a red flag.
Know When to Escalate Beyond the Core Sections
A good 10-K review also needs a clear rule for when to go deeper. Follow audit, control, liquidity, legal, market-risk, governance, or contract issues wherever the filing points. The evidence should set the stopping point.
Read the auditor’s report and controls disclosure
Read the auditor’s report for the exact opinion and the basis for it. A qualified opinion, adverse opinion, or disclaimer of opinion is different from a critical audit matter. Where the rules apply, a critical audit matter points to an audit area that required especially challenging, subjective, or complex judgment. A critical audit matter does not by itself change the audit opinion or mean the financial statements are misstated.
Item 9A covers disclosure controls and internal control over financial reporting. A material weakness deserves a deeper check, not a fixed buy or sell rule. Ask what process failed, which accounts are affected, whether a misstatement occurred, how long the fix has been underway, and whether the weakness repeats.
Check Item 9, market risk, legal matters, and exhibits when relevant
Do not rely on Item 9 alone to find an auditor change. Changes in the certifying accountant are usually reported on Form 8-K under Item 4.01. Item 9 of Form 10-K has narrower disclosure about certain disagreements and related accounting matters. Item 7A can matter when interest rates, currencies, raw-material prices, or other market risks are central to the business. Item 3 can surface major legal cases, and Item 1C can matter when cyber risk affects the thesis. Exhibits may contain debt agreements, major contracts, deal terms, and officer certifications that matter once a concern points you there.
If Part III uses incorporation by reference, follow the named definitive proxy or information statement. Do not treat the missing governance or pay detail as an omission.
A going-concern disclosure, debt covenant problem, or qualified opinion is serious. None of those facts, by itself, predicts a restatement or means a position must be sold. Those facts change the risk view and call for deeper work on liquidity, financing options, the firm’s ability to keep operating, and the investor’s own exposure. The bankruptcy guide can help organize solvency ratios, but no single model replaces a case-specific review.
Use This Repeatable 10-K Checklist
A good 10-K review leaves a short record of what changed, what matched, what did not, and what evidence would change your conclusion. This checklist turns the filing into a decision record you can reuse instead of a single score.
- Open the filing in SEC EDGAR: Confirm the form, fiscal year, filing date, amendment status, filer status, and any cover-page flags for corrected financial statements or compensation recovery.
- Choose your reading mode: Use a first-time review, annual review, or red-flag check.
- Write the current thesis in one sentence: Name the operating driver and the assumption most likely to fail.
- Compare Item 1 and Item 1A with the prior year: When Item 1A is present, record risks that are new, removed, more detailed, or moved. Treat reordering as a prompt to investigate, not as a formal importance ranking.
- Read Item 7 for the company’s explanation of what changed: Pull out concrete drivers of revenue, margins, liquidity, capital spending, and estimates.
- Reconcile Item 7 with Item 8: Follow the explanation through the primary financial statements and the relevant notes.
- Read the audit report and Item 9A: Note the opinion, critical audit matters, material weaknesses, and remediation status.
- Escalate where the evidence points: Add Item 7A, Item 3, Item 9, governance disclosures, proxy material, or exhibits as needed.
- Check what was filed after the 10-K: Before using the annual report for a current decision, look for a later 10-Q, 8-K, or 10-K/A that updates the issue you are checking.
- Write a decision memo: Separate confirmed facts, unresolved questions, and the specific evidence that would change the thesis.
SEC EDGAR provides free public access to company filings and lets you search by company, ticker, CIK, form, and filing date. Use the filed document rather than a third-party summary when the wording, footnotes, or amendments matter.
Official tools: Search SEC filings in EDGAR, use the SEC’s current Form 10-K for the filing structure, and use Investor.gov’s 10-K/10-Q guide for investor-oriented explanations.
FREE WORKSHEET
10-K Review Worksheet
Use this printable worksheet to record why you opened the filing, what changed in the business and risks, whether management’s explanation matches the numbers, and what remains unresolved before you make a decision.
Frequently Asked Questions About How to Read a 10-K
What is a 10-K?
A 10-K is the annual report most U.S. public companies file with the SEC. It covers the business, material risks, management’s discussion, audited financial statements, notes, controls, governance information, and other required disclosures. Foreign private issuers usually use Form 20-F instead.
What part of a 10-K should I read first?
For a new company, start with Item 1 Business and Item 1A Risk Factors when it is present. For an existing holding, compare the current and prior filing, then focus on changed risks, Item 7 MD&A, Item 8 statements and notes, the audit report, and Item 9A controls. The reason for reading should determine the order.
Do I need to read a 10-K cover to cover?
For a new company, a broad read often helps because the business model, segments, accounting choices, and risks are still unfamiliar. Repeat reviews can be more focused, but any material change should be followed across every related section and note. Skimming three fixed sections is not a one-size-fits-all substitute.
Are 10-K risk factors only boilerplate?
Some language is generic or repeated, but the section can still be informative. When Item 1A is present, compare it with the prior year and look for risks that are new, removed, more detailed, or moved. A change in placement is a reason to check further, not proof that the company formally ranks the risk as more important. Research also finds that risk-factor content varies with the type and level of risk firms face.
When is a 10-K due?
The deadline depends on filer status. Large accelerated filers have 60 days after fiscal year-end, accelerated filers have 75 days, and all other registrants have 90 days under the current Form 10-K instructions. Check the cover page and the SEC filing guidance rather than assuming every company has the same deadline.
How to Read a 10-K: The Bottom Line
The right depth depends on the task, so start with what you need to learn. Map the business and its main risks when the company is new to you. For an annual review, compare the current filing with the prior year and reconcile management’s explanation with the statements and notes. When a warning appears, follow it into the auditor’s report, controls, cybersecurity disclosure, legal disclosures, market-risk section, governance material, or exhibits.
Before closing the filing, write four lines: what changed, what matched the numbers, what is still open, and what evidence would change your thesis. Then check whether a later 10-Q, 8-K, or amendment has changed any of those answers.
Check the open issue most likely to change cash flow, solvency, or the business model before you add to, reduce, or simply keep the position.
YOUR TURN
Which disclosure in the latest 10-K of your largest individual holding would most likely change your thesis?
- SEC Form 10-K and Investor.gov: The current Form 10-K is the structural authority for filing items, filer deadlines, cover-page indicators, incorporation by reference, and Items 1A-1C, 7, 7A, 8, 9, and 9A. Investor.gov is used for investor-oriented explanations of company and SEC roles.
- Dyer, Lang, and Stice-Lawrence (2017): Used only for the 1996-2013 sample, filing-length trend, and concentration of growth in three disclosure topics. The paper states that those topics extend across major sections.
- Campbell et al. (2014): Used to support the narrower claim that mandatory risk-factor disclosures contain information related to firm risk and market assessments.
- PCAOB AS 3101: Used to distinguish an unqualified audit opinion and critical audit matters from qualified opinions, adverse opinions, and disclaimers of opinion.
- Method: This article uses an SEC-aligned decision router. It compares management explanations with the financial statements, notes, audit and control disclosures, and other filing sections when the issue requires escalation. It does not model investment returns.
- Limits: This checklist does not replace company-specific accounting expertise, legal review, industry context, valuation work, or professional advice.
AI-assisted tools were used for source organization and drafting support. Danny Hwang reviewed the complete article, checked the cited primary and academic sources, and approved the final wording under TheFinSense’s editorial policy.
Update history
-
v2.2
2026-08-21
FACTUAL
Updated the guide to the current Form 10-K structure, added Item 1C cybersecurity and post-10-K filing checks, clarified auditor-opinion terminology and Item 9 routing, expanded the financial-statement cross-check, and normalized internal links and trust-package markup.
-
v2.1
2026-07-20
EDITORIAL
Moved repeated correction commentary out of the Bottom Line, added a practical MD&A-to-statements reconciliation example, and clarified reader-facing wording without changing the article’s factual conclusions.
-
v2.0
2026-07-19
CORRECTION
Rebuilt the article after source review showed that three disclosure topics were incorrectly treated as three exclusive reading sections. Removed the unsupported scoring model, calculator, dollar exposure, fixed threshold, and investment-action rules.
-
v1.0
2026-04-28
PUBLISH
Original publication.